There are three things shaping conversations with buyers and sellers right now: a new kind of development showing up in more neighborhoods (especially in PA), a mortgage rate story that’s more complicated than headlines imply, and why more sellers are offering concessions. Instead of leaving you in the dark on any of these hot topics, we decided to cover all three right here. Here’s what you need to know on each, and what it means if you’re buying or selling in the Reading PA housing market right now.
What Data Centers Could Mean for Your Neighborhood
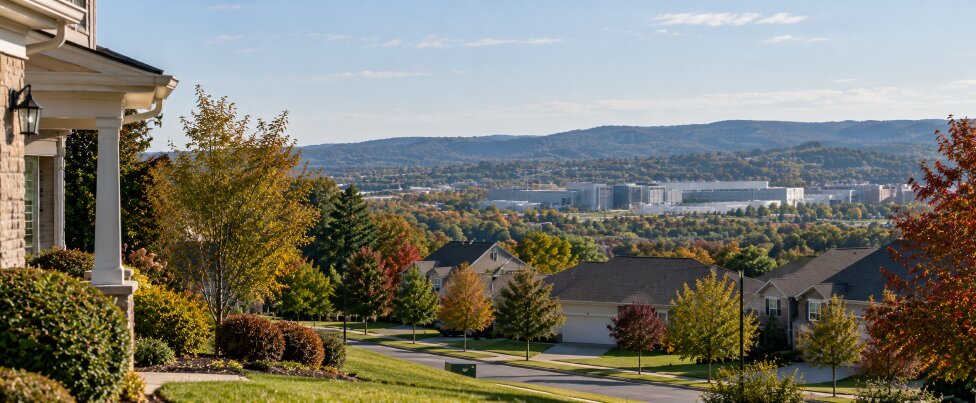
Data centers are popping up in more communities than ever. In 2015, only about a dozen ZIP codes nationwide had a large one. By mid-2026, that number had grown past 100, with more on the way. Our home state of Pennsylvania is one of the states seeing the most growth, alongside Texas, Virginia, Georgia, Ohio and a handful of others. So if you’ve heard about one coming to your area, or you’re buying and wondering what it means for a property you’re considering, here’s the honest answer: so far, the research doesn’t show a clear pattern of home values rising or falling just because a data center moved in nearby. Communities with large data centers have generally tracked similarly to comparable communities without them, with listing prices showing only a modest bump around opening. That said, every situation is different. Distance from the facility, what else gets built alongside it, and how the local infrastructure responds can all factor in. On the upside, these projects often bring property tax revenue and upgrades to roads, power, and fiber. On the practical side, it’s worth understanding what’s planned near any property before you commit. If you’ve got a specific address or neighborhood you’re wondering about, that’s exactly the kind of question we’re happy to dig into with you.
What Does It Take to Win Over Buyers Today?
If you’re thinking about selling, know this: buyers today are looking past the price tag to what it’ll actually cost them to buy, move in and settle. Affordability is tight, and buyers have more homes to choose from than they’ve had in years. One sign of how much the table has moved: 45% of recent sellers gave the buyer some kind of concession, the highest share for this time of year since at least 2020. Roughly one in seven sellers both lowered the asking price and added a concession on top of it. These seller concessions in 2026 don’t necessarily mean giving up a big chunk of your sale price. A concession can mean covering part of closing costs, taking care of a repair, or offering a credit, whatever actually moves the needle for a buyer without giving away more than necessary. New construction adds another layer. Nearly one in five newly built homes now comes with some kind of buyer incentive, most often a reduced mortgage rate through a rate buydown. If there’s new construction near your listing, that’s part of what you’re competing with. The good news: you have the same flexibility a builder does. You can offer a rate buydown, negotiate on price, help with closing costs or handle a repair. Or your strongest card might be something no new build can match: your location, your lot, your neighborhood or the character of the home itself. This is where it helps to have someone who knows exactly what’s moving in your specific corner of Berks County. Let’s talk through what makes sense for your situation before you list.
Current Mortgage Rates in Berks County: The Number You See Isn’t Always the Number You Get
Mortgage rates have climbed to their highest point since November 2023, and that headline number comes with an asterisk most people miss: it wasn’t calculated for you specifically. There isn’t one mortgage rate everyone gets. What you actually qualify for comes down to a handful of personal factors:
- Credit score: not just whether you pay on time, but how much of your available credit you’re using and how long you’ve held your accounts
- Debt-to-income ratio: your monthly debt payments divided by your monthly income; the higher it is, the higher your rate tends to run
- Down payment and loan-to-value ratio: how much you’re putting down versus how much you’re borrowing against the home’s value
- Loan type and term: different programs come with different rates, and your lender can walk you through what fits
Even after you’ve found a home, there’s still room to adjust the numbers. A mortgage rate buydown lets you pay an upfront cost for a lower rate and monthly payment, and sometimes a seller is willing to cover that as part of the deal. Negotiating seller concessions can also free up cash you could put toward a bigger down payment or paying down debt, both of which can help your actual rate. If you want to know your real number instead of guessing from some headlines you’ve read, the next step is talking to a lender and getting pre-approved, not just pre-qualified. We can point you toward people we trust, and help you figure out what to negotiate for before you get there. Whether it’s a data center near a listing, a rate that doesn’t match what you expected, or figuring out what to offer a buyer, we’re talking about this stuff with customers every week. Reach out, and let’s dig into yours.